What Is a Good Dividend Yield in 2026?
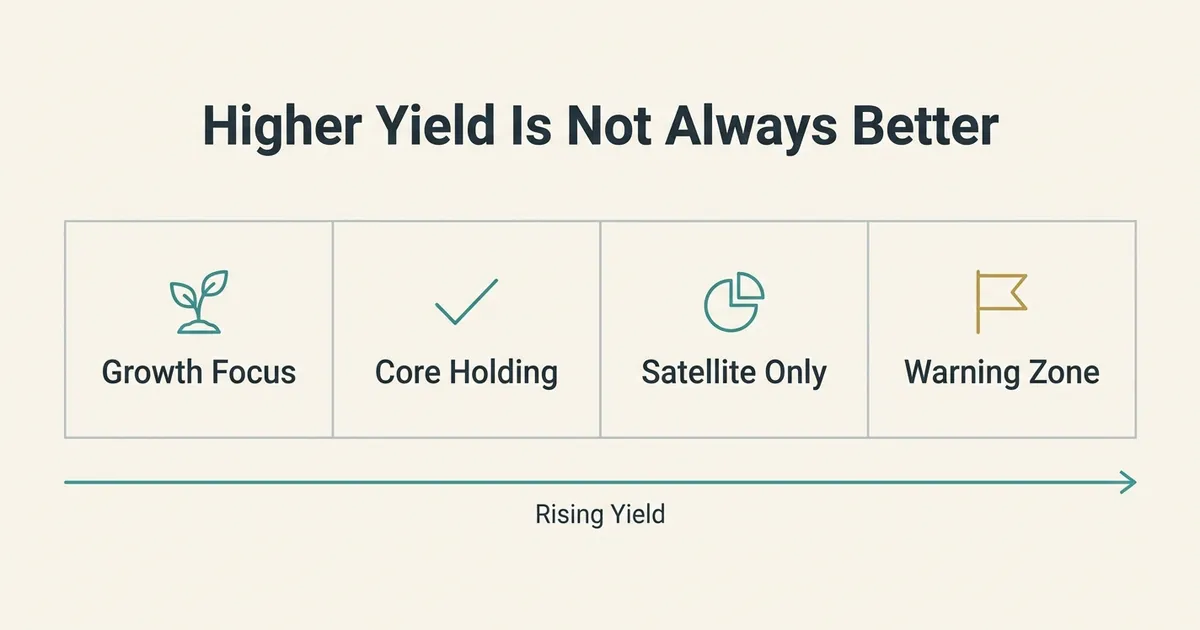
A good dividend yield for most portfolios sits between 2% and 6%, high enough to generate meaningful income but low enough to signal a sustainable payout. Yields above 7%–8% often flag financial trouble at the underlying company rather than exceptional value — a pattern known as a dividend yield trap.
For a parent building a custodial brokerage account, the right yield depends on time horizon, not just the headline percentage. According to Hartford Funds (2026), dividend income contributed an average of 33% of the S&P 500's total return from 1940 through 2025, a mechanism that matters more the longer a child's money stays invested — often 10 to 18 years before an account holder reaches the age of majority set by state UTMA/UGMA law.
A stock or fund's yield is not fixed — it moves inversely with price, so a falling share price can inflate the percentage even as the company cuts its payout. Understanding that relationship, covered in the formula section below, keeps you from mistaking a shrinking business for a high-income bargain when you're building passive dividend income in a custodial brokerage account.
What Is Dividend Yield and How Is It Calculated?
Dividend yield equals a company's or fund's total annual dividends per share divided by its current share price, expressed as a percentage. According to the SEC's Investor.gov (2025), this formula lets you compare the income return of stocks or funds trading at very different prices, since a $200 stock and a $20 stock can pay the same relative yield.
The formula: Dividend yield = (Annual dividends per share ÷ Current share price) × 100.
Consider a real example. According to StockAnalysis.com market data (September 2026), the Schwab U.S. Dividend Equity ETF (SCHD) paid about $1.05 per share in trailing twelve-month dividends against a share price near $33.10 on September 24, 2026: $1.05 ÷ $33.10 = 0.032, or roughly a 3.2% yield. That figure moves daily as the share price moves, even though the announced dividend per share stays fixed until the fund's next declaration date.
What Counts as a Good Dividend Yield for a Custodial Account?
A good dividend yield for a child's custodial account falls in the 2%–4% range for a core holding, with up to 6% acceptable for a smaller income-tilted slice. That range balances real income against the payout coverage a company or fund needs to keep paying you for the next decade.
Context for that range: According to S&P dividend data compiled by Multpl (August 2026), the S&P 500's trailing dividend yield stood near 1.06% at the end of August 2026, well below its long-run average and close to its lowest level on record. Dividend-growth benchmarks run a bit richer — the ProShares S&P 500 Dividend Aristocrats ETF (NOBL), which tracks companies that have raised payouts for 25+ consecutive years, yielded around 2.1% on September 24, 2026, per StockAnalysis.com market data (September 2026). Real estate investment trusts (REITs) run higher still: according to Nareit (August 2026), the FTSE Nareit All Equity REITs Index yielded approximately 3.8% as of August 31, 2026, reflecting the sector's high required payout. Bonds are the other yardstick: the 10-year Treasury yielded 5.11% on September 23, 2026, per Federal Reserve data published on FRED (September 2026), so a dividend fund now has to earn its place through dividend growth rather than headline income alone.
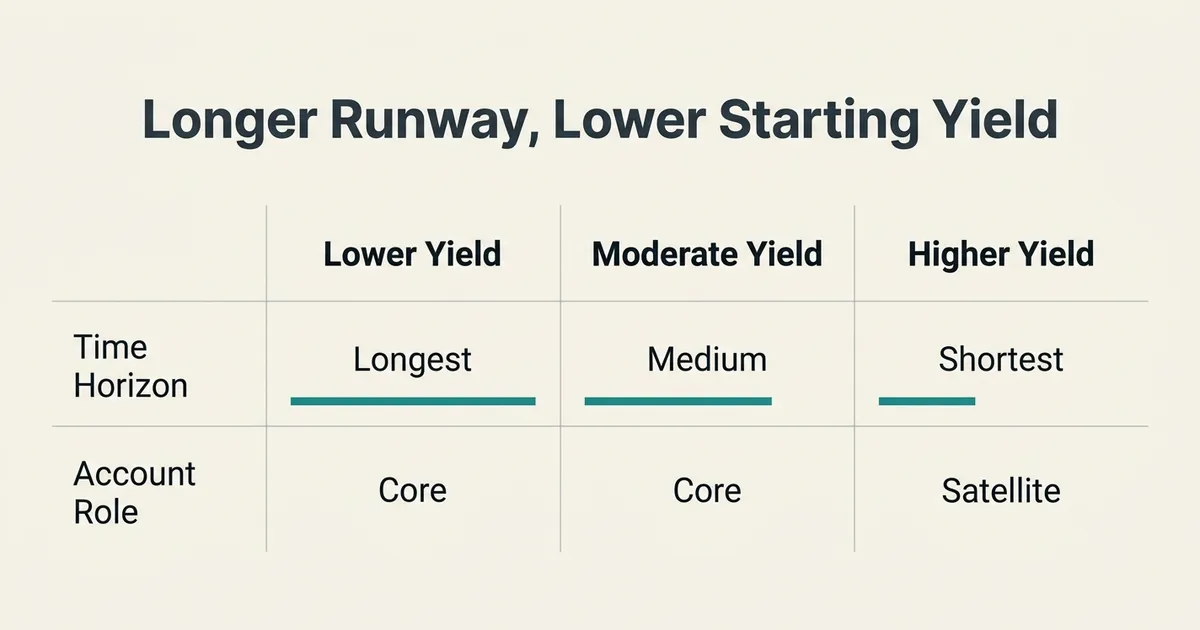
Decision rule: choose a 1%–2% yield fund if your child is under 5 and you have 15+ years before the money is needed, because dividend growth compounds faster than current income at that stage. Choose 2%–4% if your child is 6–10 and you want visible, reinvestable income now while still holding mostly blue-chip, dividend-growing companies. Avoid anchoring a core custodial position above 6% — that's a satellite allocation at most, not a foundation.
What Does a 5% Dividend Yield Mean for Your Child's Portfolio?
A 5% dividend yield means the holding pays $5 a year in dividends for every $100 of share price — $500 a year in pre-tax income on a $10,000 position. Yields near 5% typically show up in REITs and utilities rather than growth-oriented blue chips.
The mechanism: REITs are required to distribute most of their taxable income to shareholders to keep their tax-advantaged structure, which pushes their yields above the broader market's. Under Internal Revenue Code Section 857, a REIT must distribute at least 90% of its taxable income to shareholders to keep its special tax treatment, which is why a holding like Realty Income Corporation yielded about 5.9% on September 24, 2026, per StockAnalysis.com market data (September 2026). That structural requirement makes REIT dividends more predictable in normal conditions but more exposed during a real estate downturn, since there's less retained earnings cushion.
Worked example: a parent contributing $200 a month into a 5%-yield REIT-heavy fund, with dividends reinvested through a dividend reinvestment plan (DRIP) and a hypothetical 6% average annual total return, would reach roughly $32,900 after 10 years — illustrative math only, since real returns fluctuate and are never guaranteed.
What Does a 10% Dividend Yield Mean — and Why Is It a Red Flag?
A 10% dividend yield means the annual dividend equals 10% of the current share price, a level that usually signals the market doubts the payout will last, not that you've found a bargain. Yields this high are rare among healthy, diversified businesses.
Here's the mechanism worth internalizing: yield rises mechanically whenever a stock's price falls faster than its dividend is cut, so a 10% yield often reflects a recent price crash rather than a generous company. Treat an unusually high yield as a signal to investigate payout sustainability before buying, because the market is frequently pricing in a future dividend cut that hasn't been announced yet. Leveraged, income-focused sectors run structurally higher: Annaly Capital Management, a mortgage REIT, yielded about 14.6% on September 24, 2026, per StockAnalysis.com market data (September 2026), reflecting the leverage and interest-rate sensitivity built into its mortgage-backed-securities business model.
Decision rule: never place a custodial account's core holding in anything yielding above 8% unless you fully understand — and are comfortable explaining to your child later — why the payout is that high. A double-digit yield belongs in the "understand the risk first" bucket, not the "set it and forget it" bucket a busy parent wants for a $50–$500/month account.
How Much Would You Need to Invest to Make $1,000 a Month in Dividends?
To collect $1,000 a month — $12,000 a year — in dividends, divide $12,000 by your target yield. At a 3.5% yield, that's $12,000 ÷ 0.035 = $342,857 invested; at a 2% yield you'd need $600,000; at a 6% yield, roughly $200,000.
For context on that 3.5% figure: SCHD's trailing yield was about 3.2% in late September 2026, per StockAnalysis.com market data (September 2026), so 3.5% is a slightly optimistic assumption for a broad dividend fund. For a family starting with $50–$500 a month, this is a long-horizon target, not a near-term one. A parent contributing $300 a month, with dividends reinvested automatically and a hypothetical 7% average annual total return, would reach a comparable $340,000-plus balance in roughly 29 years — well past a typical custodial-account transfer age, meaning the goal is usually completed inside the child's own adult brokerage account, not the custodial one. That math is illustrative only; it ignores taxes, fees, and the reality that markets don't post the same return every year.
Which Dividend Yield Range Fits a Custodial Account Timeline?
The table below compares common dividend yield tiers using trailing twelve-month yields as of September 24, 2026, per StockAnalysis.com market data (September 2026), with expense ratios from each fund issuer. Yields move daily with share prices.
| Yield tier | Example holding | Approx. yield (2026) | Expense ratio | Payout risk | Best fit for a custodial account |
|---|---|---|---|---|---|
| Low (0–2%) | Vanguard Dividend Appreciation ETF (VIG) | ~1.5% | 0.04% | Low — dividend-growth focus | Ages 0–5, 15+ year horizon, growth priority |
| Moderate (2–4%) | Schwab U.S. Dividend Equity ETF (SCHD) | ~3.2% | 0.06% | Low-moderate | Ages 0–10, blend of income and growth |
| High (4–6%) | Realty Income (O) | ~5.9% | N/A — individual stock | Moderate — single REIT, sector concentration | Satellite position, 5–10% of portfolio |
| Very high (7%+) | JPMorgan Equity Premium Income ETF (JEPI) | ~8.1% | 0.35% | High — covered-call strategy caps upside | Avoid as a core holding for a young child |
| Extreme (10%+) | Annaly Capital Management (NLY) | ~14.6% | N/A — individual stock | Very high — leveraged mortgage REIT | Avoid; classic yield-trap example |
Read it this way: a parent with a child under 5 and a 15+ year runway wins by leaning on the low and moderate tiers, since dividend growth compounds into a much larger income stream than a static high yield ever does. A parent closer to needing the money — say, for a child turning 10 with extracurricular costs in mind within 5–8 years — can add a moderate slice of the high tier for visible income, but should treat the two bottom tiers as holdings to research individually, not to buy for a child's account on yield alone. For a deeper breakdown of single-stock versus fund construction, see our comparison of dividend ETFs vs. individual stocks and our list of best dividend stocks for a custodial account.
How Does the Kiddie Tax Affect Dividend Yield Choices?
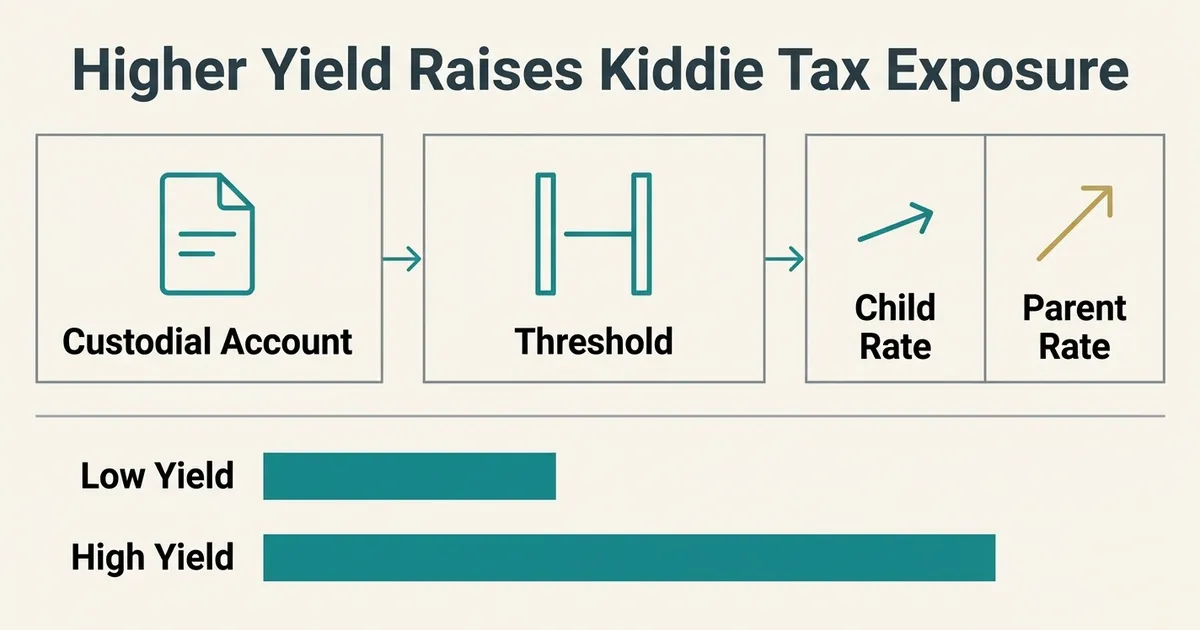
The kiddie tax can push a child's dividend income above a modest threshold into taxation at the parent's marginal rate, which can reach 37% — a strong argument for not over-concentrating in high-yield holdings inside a custodial account. This is a federal rule and applies regardless of which state's UTMA or UGMA statute governs the account.
According to IRS Revenue Procedure 2025-32 (2025), for the 2026 tax year the first $1,350 of a child's unearned income — which includes dividends — is generally tax-free, the next $1,350 is taxed at the child's own rate, and anything above $2,700 is taxed at the parent's marginal rate under the kiddie tax rules. The calculation is reported on Form 8615 (IRS, 2025), and those thresholds are unchanged from 2025 despite annual inflation indexing, so don't assume they rose. According to IRS Publication 550 (2025), qualified dividends retain preferential capital-gains tax rates (0%, 15%, or 20% depending on income) even when taxed at the parent's rate, which is more favorable than ordinary-income treatment but still a real cost above the threshold.
Decision rule: if the dividends and other unearned income in a single custodial account are approaching $2,700 a year, favor the 1%–3% yield tier over the 5%+ tier to slow how fast unearned income crosses the kiddie-tax line, and consider splitting large gifts across a custodial account and a 529 plan — compare the tax treatment of both in our custodial account vs. 529 plan guide.
On account structure: under California Probate Code Section 3920.5, UTMA assets in California generally transfer to the child at age 18; a parent making an outright gift can specify a later age up to 21, while property left by will or trust can be held until as late as 25. Most other states set the UTMA/UGMA transfer age between 18 and 21, and some allow a later age, so verify your own state's statute before assuming California's rules apply.
What Mistakes Do Parents Make When Chasing Yield?
The most common mistake is buying the highest advertised yield without checking whether the payout is covered by earnings, which is how parents end up owning a fund like the extreme tier above without realizing the risk. A high yield with an uncovered payout is a countdown to a dividend cut, not a bonus.
Charles Schwab's investor education on dividend stocks notes that a payout ratio — dividends paid divided by net income — above 80% leaves a company little cushion to keep paying during an earnings downturn, and ratios above 100% mean the company is paying out more than it earns. Three other mistakes compound this one: concentrating a custodial account in one or two high-yield individual stocks instead of a diversified fund; ignoring dividend growth rate in favor of the current yield snapshot, which undervalues holdings like VIG that raise payouts steadily; and leaving dividends sitting in cash instead of automating reinvestment. A DRIP turns a 3% yield into meaningfully more account growth over a decade purely through compounding — see our step-by-step DRIP auto-compounding setup guide for how to turn it on inside a custodial brokerage account.
Disclaimer: This article is for general educational purposes and does not constitute personalized investment, tax, or legal advice. Dividend yields, expense ratios, and tax thresholds change over time — verify current figures with the fund issuer, the IRS, and your state's UTMA/UGMA statute, or consult a licensed financial or tax professional before acting.
Frequently asked questions
What does a 5% dividend yield mean?
A 5% dividend yield means the company or fund pays $5 in annual dividends for every $100 of share price, or $500 a year in pre-tax income per $10,000 invested. Yields near 5% are common among REITs, which must distribute at least 90% of taxable income to shareholders under Internal Revenue Code Section 857, so REIT yields typically run well above the S&P 500's trailing yield of roughly 1.06% at the end of August 2026, per S&P dividend data compiled by Multpl (August 2026).
How do I make $1000 a month in dividends?
To collect $1,000 a month, or $12,000 a year, in dividends, divide $12,000 by your target fund's yield — at a 3.5% yield, a little above the roughly 3.2% trailing yield of the Schwab U.S. Dividend Equity ETF in late September 2026 per StockAnalysis.com market data (September 2026), that requires about $342,857 invested. A parent contributing $300 a month and reinvesting dividends automatically through a DRIP could reach a comparable balance in roughly 29 years at a hypothetical 7% average annual total return, though actual results vary with market performance and are never guaranteed.
What does a 10% dividend yield mean?
A 10% dividend yield means the annual dividend equals 10% of the current share price, a level that should prompt a check on payout sustainability rather than read as a sign of exceptional value. Yields this high usually follow a steep price decline or appear in structurally leveraged sectors like mortgage REITs — Annaly Capital Management, for example, yielded about 14.6% on September 24, 2026, per StockAnalysis.com market data (September 2026) — and often precede a dividend cut rather than years of stable income.
What is a good dividend yield?
A good dividend yield for most long-term portfolios, including a child's custodial account, falls between 2% and 6%, balancing meaningful income against payout sustainability. Growth-focused funds like the Vanguard Dividend Appreciation ETF yield around 1.5%, while the S&P 500's own trailing yield of roughly 1.06% at the end of August 2026, per S&P dividend data compiled by Multpl (August 2026), shows why anything above 7%–8% deserves extra scrutiny before you buy it for a child's account.
Dividend yield formula
The dividend yield formula divides a stock or fund's total annual dividends per share by its current share price, then multiplies by 100 to express it as a percentage. For example, a fund paying $1.05 per share annually at a $33.10 share price yields about 3.2% — $1.05 ÷ $33.10 = 0.032 — matching the calculation method described by the SEC's Investor.gov (2025).
Dividend yield calculator
A dividend yield calculator applies the same formula automatically — annual dividend per share divided by current share price — and most brokerage platforms display the result directly on a stock or ETF's quote page. To estimate monthly income by hand, multiply your invested balance by the yield and divide by 12: $15,000 invested at a 3% yield generates about $450 a year, or roughly $37.50 a month, before any tax owed under the kiddie-tax rules described in IRS Revenue Procedure 2025-32 (2025).